
Last updated October 16, 2026
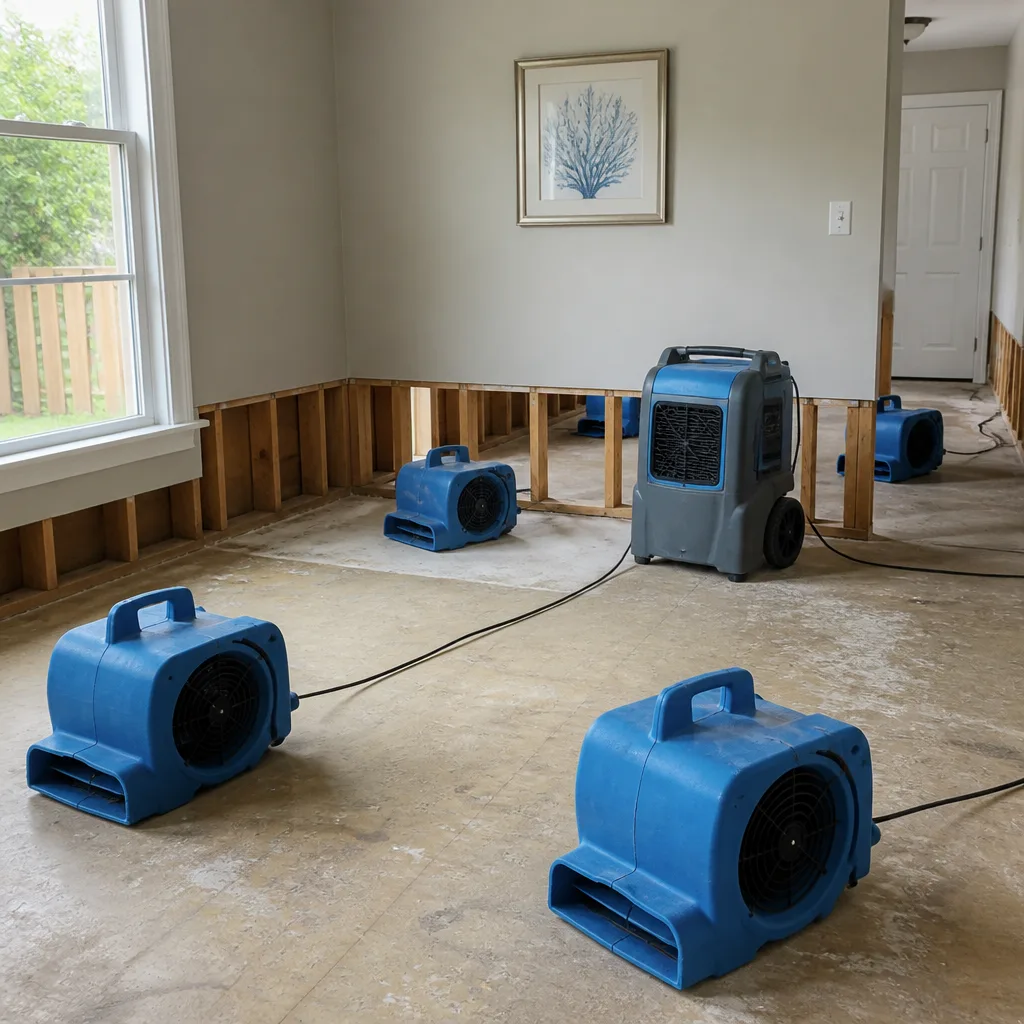 Water damage drying
 Fire & smoke cleanup
 Mold remediation
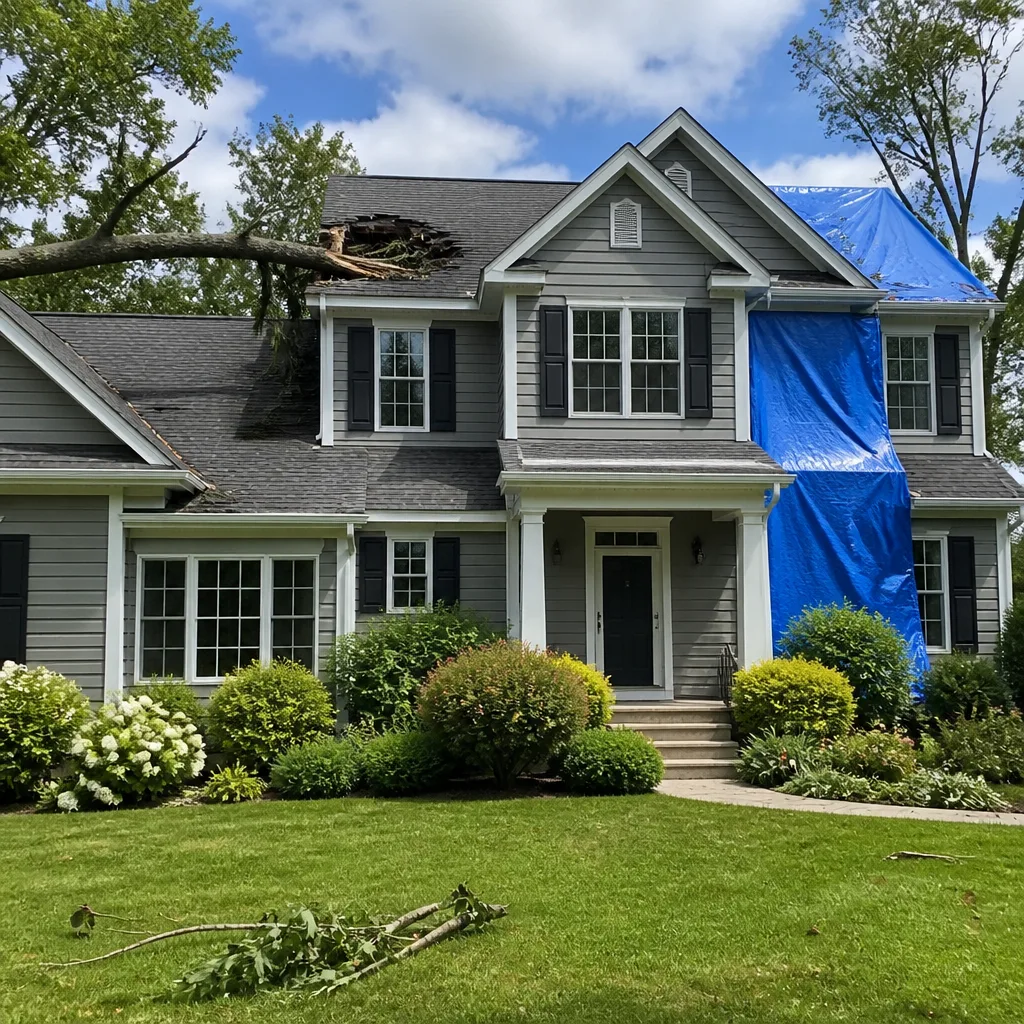 Storm response
 Sewage cleanup
 Reconstruction
Free visual inspection and a written scope of work before any mitigation begins - photos, moisture readings, and drying logs go in your claim file
The scope we write is the scope we bill. Anything new gets shown to you, in writing, before we touch it.
Get your free estimateThe Complete Guide to Damage Restoration in Fort Worth
A burst pipe in a Fort Worth attic doesn’t just cause water damage. Untreated in 72 hours it seeds mold, and the drywall smoke from the remediation torch can trigger a secondary odor claim. Most homeowners don’t find that out until the second invoice lands. This guide maps the full restoration chain so you can make one informed decision instead of three panicked ones, and you can explore more guides & resources on our blog. We’ll walk through how water, fire, and mold are actually connected, what a legitimate restoration sequence looks like, and the Fort Worth-specific risks that most national guides miss entirely.
Quick Answer
Damage restoration in Fort Worth typically means water extraction, structural drying, fire cleanup, and mold remediation handled as one connected sequence, not three separate emergencies. A single qualifying event can trigger all three damage types, and a contractor who understands that chain will document the full scope for your insurance claim. For detailed pricing context, see our Damage Restoration Cost Breakdown: The Fort Worth Homeowner’s Reference for 2026; expect to pay $3,500 – $14,000 for water restoration, $8,000 – $35,000 for fire restoration, and $2,200 – $9,000 for mold remediation, with exact pricing depending on square footage and damage class. Keegan Restoration Fort Worth provides free estimates on all three service lines.
Restoration work we handle
Table of Contents
- Why a Single Contractor Saves Money on Fort Worth Damage Claims
- The Restoration Chain: How Water, Fire, and Mold Actually Connect
- The Order of Operations: What Gets Skipped When Contractors Rush
- Restoration vs. Remediation: What the Words Mean on a Texas License
- Fort Worth-Specific Risk Factors: Clay Soil and HVAC Mold Spread
- How to Read a Scope of Work Before Signing
- Insurance Claims in Texas: What a Siloed Contractor Misses
- Common Mistakes to Avoid
- When to Call a Professional
- Frequently Asked Questions
Why a Single Contractor Saves Money on Fort Worth Damage Claims
Every restoration project has a chain of causation. A water event creates the conditions for mold. A fire event leaves behind water from suppression efforts, plus smoke residue that introduces odor. Treat each one as an isolated job and you create documentation gaps that insurance adjusters exploit. Here’s what that looks like in practice: a water mitigation crew extracts and dries, but doesn’t test for mold spores. Six weeks later you find growth in the wall cavity. The original contractor’s report doesn’t mention microbial testing. The insurance company says it’s a new claim with a separate deductible. You’re out $2,500 because the first crew didn’t understand the chain.
In Fort Worth, where summer humidity lingers above 70% for weeks, that mold window shrinks from the national 48-72 hour guideline to closer to 48 hours in unconditioned spaces. A single contractor running the full sequence means one scope of work, one chain of documentation, and one phone number for the adjuster to call. That’s not convenience. It’s claim survival.
We work to The Garrison Standard on every job: the price goes in writing before any work starts, technicians are background-checked and in uniform, and every repair is backed by the 365-Day Done Right Promise. If the repair fails within a year, we return at no charge. That guarantee only makes sense when we control the full sequence from extraction to rebuild.
The Restoration Chain: How Water, Fire, and Mold Actually Connect
Most Fort Worth homeowners treat water damage restoration in Fort Worth as a plumbing problem with extra steps. It’s not. Water damage is the initiating event in a sequence that can end in structural compromise, microbial growth, and odor claims that outlast the repair itself. Here’s the chain as we see it in the field:
- Water intrusion. A supply line fails, a storm overwhelms a foundation drain, an HVAC condensate pan overflows. Water moves along the path of least resistance, saturating drywall, wicking up baseboards, and pooling in wall cavities.
- Material saturation. Drywall acts like a sponge. Carpet padding holds water against the subfloor. Wood framing absorbs moisture into its grain. The longer materials stay wet, the deeper the moisture travels and the more structural drying is required.
- Microbial growth. Mold spores exist in every Fort Worth home, dormant until moisture and a food source activate them. Drywall paper and wood framing are perfect food sources. In warm, humid conditions, visible growth can appear in 48-72 hours and hidden growth inside cavities can begin sooner.
- Fire event complication. A kitchen fire or electrical fire gets put out with water. That water soaks the same materials the fire didn’t destroy. Now you have charred, wet, smoke-saturated materials in the same rooms. The mold risk hasn’t gone away because the fire happened; it’s compounded because of the suppression water.
- Secondary damage. Odor, warped flooring, delaminated cabinets, corrosion on electrical components. None of these show up on day one. They emerge in weeks two through eight, long after the initial emergency has passed.
Understanding this chain changes how you hire. You’re not hiring a water extraction crew. You’re hiring a sequence manager who can document the full chain for insurance purposes and prevent step three from turning into a second claim. When homeowners call us after a fire, we don’t just board up and clean soot. We run psychrometric readings, check moisture levels in the framing, and include microbial testing in the scope if conditions warrant. That’s the chain in action.
Equipment matters here. We run professional-grade drying and extraction equipment from Dri-Eaz, Phoenix, XPOWER, B-Air, and Injectidry, operated in compliance with IICRC, RIA, and IFA industry standards. A homeowner-grade box fan and a rented dehumidifier from the hardware store will not dry a wall cavity. The IICRC sets minimum performance thresholds for drying equipment, and professional desiccant dryers hit those thresholds while retail equipment does not.
The Order of Operations: What Gets Skipped When Contractors Rush
The restoration sequence for any Fort Worth damage event follows a disciplined order. Skip a step and you’re paying for it twice. Here’s the actual sequence, with what gets cut when a contractor rushes to the rebuild phase:
- Assessment and documentation. The contractor maps the full extent of the damage, takes moisture readings, photographs everything, and writes a scope of loss. This is the step that makes or breaks your insurance claim. A rushed assessment means missed damage and a scope that doesn’t cover the full chain. What gets skipped: thermal imaging, moisture mapping in adjacent rooms, documentation of pre-existing conditions that protect your claim.
- Extraction. Standing water is removed using professional extraction equipment. For sewage or flood water, this step includes controlled demolition of saturated porous materials. What gets skipped: extraction in wall cavities and under cabinets, where water hides and mold begins.
- Structural drying. Professional-grade air movers and desiccant or refrigerant dehumidifiers are placed to dry the full affected area. Psychrometric readings track moisture content daily until dry standard is reached. What gets skipped: daily moisture logging, drying records that insurance adjusters need to close the claim, drying of framing behind intact drywall.
- Assessment again. Post-drying inspection confirms the structure is dry and documents any remaining damage. This second assessment is where a competent contractor catches what was missed in the initial chaos. What gets skipped: microbial testing, structural inspection for hidden compromise, smoke odor assessment after fire events.
- Rebuild. Only after the structure is verifiably dry and clean does rebuild begin. Drywall, flooring, cabinetry, paint. What gets skipped: nothing in the rebuild phase, because all the skips happened upstream. The rebuild itself is straightforward if steps one through four were done correctly.
In our experience, the step most often skipped by low-bid contractors in Fort Worth is daily moisture logging during structural drying. An adjuster receiving a scope without drying logs will question the entire claim. The documentation gap becomes an insurance gap. We document every job to IICRC standards and format the documentation to support your insurance claim. That’s not a bonus service. It’s the difference between a claim that closes and a claim that drags out for months.
Restoration vs. Remediation: What the Words Mean on a Texas License
A Texas contractor’s license classification matters, and most homeowners never ask about it. “Restoration” and “remediation” are not interchangeable words. Restoration means returning a structure to its pre-loss condition. Remediation means removing or correcting a hazard, typically mold or other contaminants. A contractor who only restores has no business remediating mold, and a mold-only contractor shouldn’t be managing a structural rebuild.
Here’s why this distinction affects your warranty: if a restoration contractor does mold work without proper remediation credentials or protocols, your year-one warranty from that contractor may not cover mold regrowth. The contractor can argue they performed restoration, not remediation. You’re left with a mold problem and no standing to make them fix it.
Keegan Water Damage Restoration provides water damage restoration, fire damage restoration, and mold remediation. We run all three service lines under one standard: The Garrison Standard. The price is in writing before work begins. Technicians are background-checked and arrive in uniform. Every repair carries the 365-Day Done Right Promise, a written one-year guarantee with a free return visit if the work fails. One contractor, full scope, no gap between restoration and remediation.
When you’re comparing bids in Fort Worth, ask the direct question: “Does your Texas license cover mold remediation, or only restoration?” A licensed contractor running proper protocols will answer clearly. A contractor who hedges or changes the subject is telling you something about their scope.
Fort Worth-Specific Risk Factors: Clay Soil and HVAC Mold Spread
Fort Worth has two structural risk factors that most national restoration guides never mention. The first is the soil. Most of Fort Worth sits on expansive clay soil, the same gumbo clay that runs through much of North Texas. Clay soil expands when wet and contracts when dry. After a flood or a major leak, the soil around your foundation can shift, causing slab movement, drywall cracking, and door frame misalignment. A restoration contractor who doesn’t understand clay soil will treat the interior damage and miss the foundation movement. Six months later, the cracks are back and your insurance file is closed.
The second risk factor is the HVAC system. Fort Worth summers push outdoor humidity above 80% for weeks, and indoor mold spread happens through ductwork. A mold remediation job that cleans the walls but doesn’t assess the HVAC system is incomplete. Mold spores circulate through returns, settle in the blower cabinet, and recolonize the moment conditions turn favorable. A proper mold remediation scope in Fort Worth includes HVAC assessment, coil cleaning when needed, and sometimes duct decontamination. We run Injectidry systems and other professional-grade drying equipment in compliance with IICRC standards when we assess an affected Fort Worth home. The brand of equipment matters less than the protocol, but protocol without proper equipment is just estimates.
These two factors create a Fort Worth-specific restoration sequence. Address the water. Check the foundation for clay soil movement. Assess the HVAC system for spore distribution. Document all of it. Skip any of these and you’re treating symptoms, not the system that created them.
How to Read a Scope of Work Before Signing
The scope of work is a written document that lists every task the contractor will perform, every material they’ll use, and the total price. It’s the contract. It’s also where contractors bury three line items that cost homeowners thousands. Here’s how to read one:
Line item one: “If additional damage is discovered during the work, cost to be determined.” This is the cost-mover’s clause. It lets a contractor start a job with a low bid and then escalate the price once the walls are open. A legitimate scope should state that additional damage will be documented, photographed, reviewed with the homeowner, and priced in writing before the extra work begins. If the scope doesn’t say that, it says the opposite.
Line item two: “Cleaning of affected areas per industry standards.” Which industry? Which standards? A $400 cleaning and a $2,400 cleaning can both be described as “per industry standards.” Your scope should name the standard. IICRC, RIA, and IFA are the professional standards bodies in the restoration industry. If the scope references them by name, you’re working with a contractor who runs protocols, not guesswork.
Line item three: “Disposal of affected materials.” How much disposal? Which materials? Whose dumpster? A vague disposal line can turn into a $1,500 add-on at the end of the job. Your scope should itemize the disposal scope: the estimated volume, the material types, and the disposal method. If it’s not itemized, it’s an open line item.
Read the scope the same way you’d read a contract for a new build. Every line item should have a number attached to it, in writing, before work starts. That’s The Garrison Standard. That’s what Keegan Restoration Fort Worth delivers on every job. If a contractor says the scope is “close enough” or “you can trust us,” you’ve learned something important about how they’ll behave on day three.
Insurance Claims in Texas: What a Siloed Contractor Misses
Insurance claims in Texas treat water, fire, and mold damage differently, and the documentation standard for each is different. A contractor who only handles one damage type will miss documentation requirements for the other two. Here’s the practical impact:
Water damage claims require proof of causation. The adjuster needs to see the source, the path, and the affected materials. If your water mitigation contractor doesn’t document the source clearly, the insurer can argue the damage was pre-existing or excluded. Fire damage claims require proof of cause and origin, plus a line-by-line inventory of affected contents. If your fire restoration contractor doesn’t document contents thoroughly, you’re arguing about a sofa, not a structure. Mold claims in Texas are tighter than water or fire claims. Insurers often classify mold as a maintenance issue unless the scope clearly links the mold to a covered water event. That linkage is the key document, and it only exists when a contractor documented the initial water damage before the mold appeared.
This is why the single-contractor model protects your claim. One sequence of documentation tells one story: the pipe failed, the water saturated these materials, the mold developed in this timeline, the remediation removed this many square feet, the rebuild replaced these components. A siloed contractor tells three separate stories, and the gaps between them become the insurer’s argument.
We photograph every stage. We write the scope before work begins. We log moisture daily during drying. We document the full chain. The documentation is formatted to support your insurance claim, and when an adjuster has questions, they can call the same number for every stage of the job. That is claim protection, and it’s part of The Garrison Standard.
Common Mistakes to Avoid
- Calling your insurance company before calling a restoration contractor. Insurance companies dispatch preferred vendors who work for the insurer, not for you. The vendor’s incentive is to close the claim cheaply. Call a contractor who works for you first, document the scene, then call your insurer with the facts in hand.
- Using a box fan and a home dehumidifier to “dry it out” yourself. A box fan moves air across surfaces but does not extract moisture from wall cavities. The IICRC sets drying standards that require professional-grade equipment. DIY drying creates the perfect conditions for hidden mold growth.
- Signing a scope with vague language. “Clean and restore affected areas” is not a scope. It’s an invitation to move the price at the door. Every line item needs a dollar figure next to it, in writing, before work starts.
- Hiring a water restoration company for structural rebuild. Extraction and drying are licensed restoration work. Rebuilding a wall is construction work. A contractor without construction licensing will subcontract the rebuild, and now a third party controls your finish quality.
- Thinking mold is “just in that one room.” Mold spores travel through HVAC systems, and Fort Worth summers make every home a mold incubator. If the remediation scope doesn’t include HVAC assessment, it’s incomplete.
- Waiting to document the scene. Every hour that passes changes the evidence. Water stains dry, soot settles, and mold blooms. Photograph everything immediately, before any cleanup happens.
- Accepting a verbal estimate. In Texas, verbal estimates are not binding. If the price isn’t in writing, the price doesn’t exist. This is the most basic and most common mistake in Fort Worth restoration projects.
When to Call a Professional
Call a professional the moment you discover standing water, visible mold, or fire damage that extends beyond a single burned pot. These are not inspection situations. Delaying professional assessment while damage spreads is the most expensive decision a Fort Worth homeowner can make. Learn the Damage Restoration Warning Signs: A Fort Worth Homeowner’s Reference Guide so you know when to act. You also need a professional when your insurance company requires industrial drying logs, when the damage is inside wall cavities or under flooring, when mold appears in multiple rooms, or when a fire has compromised structural framing. You can inspect, but you cannot diagnose damage you can’t see. Keegan Restoration Fort Worth offers free estimates in Fort Worth. Call (682) 900-2821 and a live person answers, 24 hours a day, 7 days a week. We’ll assess the full scope, put the price in writing, and walk you through the restoration sequence.
Frequently Asked Questions
Water damage restoration in Fort Worth typically runs $3,500 – $14,000 depending on the classification of the water, the square footage affected, and whether structural drying reaches wall cavities. Fire damage restoration typically runs $8,000 – $35,000 based on soot type, affected square footage, and whether structural rebuild is required. Mold remediation typically runs $2,200 – $9,000 depending on colony size, containment requirements, and HVAC involvement. Call (682) 900-2821 for an exact quote. Estimates are free.
Most Texas homeowner policies cover sudden and accidental water damage, fire damage, and mold remediation that directly results from a covered water event. Mold claims are the tightest: the insurer will require documentation linking the mold to the covered water event, not to a maintenance failure. A restoration contractor who documents the initial water damage before mold appears is your strongest ally in getting the mold claim covered. We format every job’s documentation to support your insurance claim and coordinate directly with your adjuster.
Keegan Restoration Fort Worth runs 24/7 live dispatch. A live person answers every call, day or night, including weekends and holidays. In water damage emergencies, we prioritize same-day assessment in Fort Worth because the 48-hour mold window is unforgiving in Texas humidity. Call (682) 900-2821 and the phone is answered by a person, not a phone tree.
If visible mold covers more than 10 square feet, the Environmental Protection Agency recommends professional remediation. Hidden mold inside wall cavities is never a cleaning job, regardless of visible square footage. The honest answer: we scope remediation by testing and inspection, not by upselling. The documentation shows what’s there. If a cleaning will resolve it, we say so. If remediation is required, the scope states exactly what and why.
We do. Our documentation is formatted to support your insurance claim, and we communicate directly with your adjuster throughout the restoration process. You don’t translate restoration terminology for an adjuster who speaks fluent claim language. That’s our job. The Garrison Standard includes full job documentation, from initial assessment through final drying logs.
We serve all of Fort Worth, including Tanglewood, Ryan Place, Fairmount, Wedgwood, Lake Worth, Benbrook, Saginaw, and surrounding areas. Our Fort Worth location dispatches uniformed, background-checked technicians across the metro. Call (682) 900-2821 to schedule a free assessment.
Conclusion
Damage restoration in Fort Worth is one connected sequence, not three separate emergencies. One event triggers the chain: water creates mold conditions, fire suppression adds water, and both compound into secondary damage. A single contractor who understands the full chain, documents every stage for your insurance claim, and runs to a written standard saves you money and prevents repeat claims. We are the fire damage restoration and mold remediation contractor in Fort Worth that runs every job to The Garrison Standard: price in writing before work starts, uniformed technicians, and a 365-Day Done Right Promise on every repair. If water is actively damaging your home right now, call (682) 900-2821. A live person answers.
Written by Shane Pruitt, Owner at Keegan Restoration Fort Worth, serving Fort Worth since 2005.
See the difference
 Before
 After
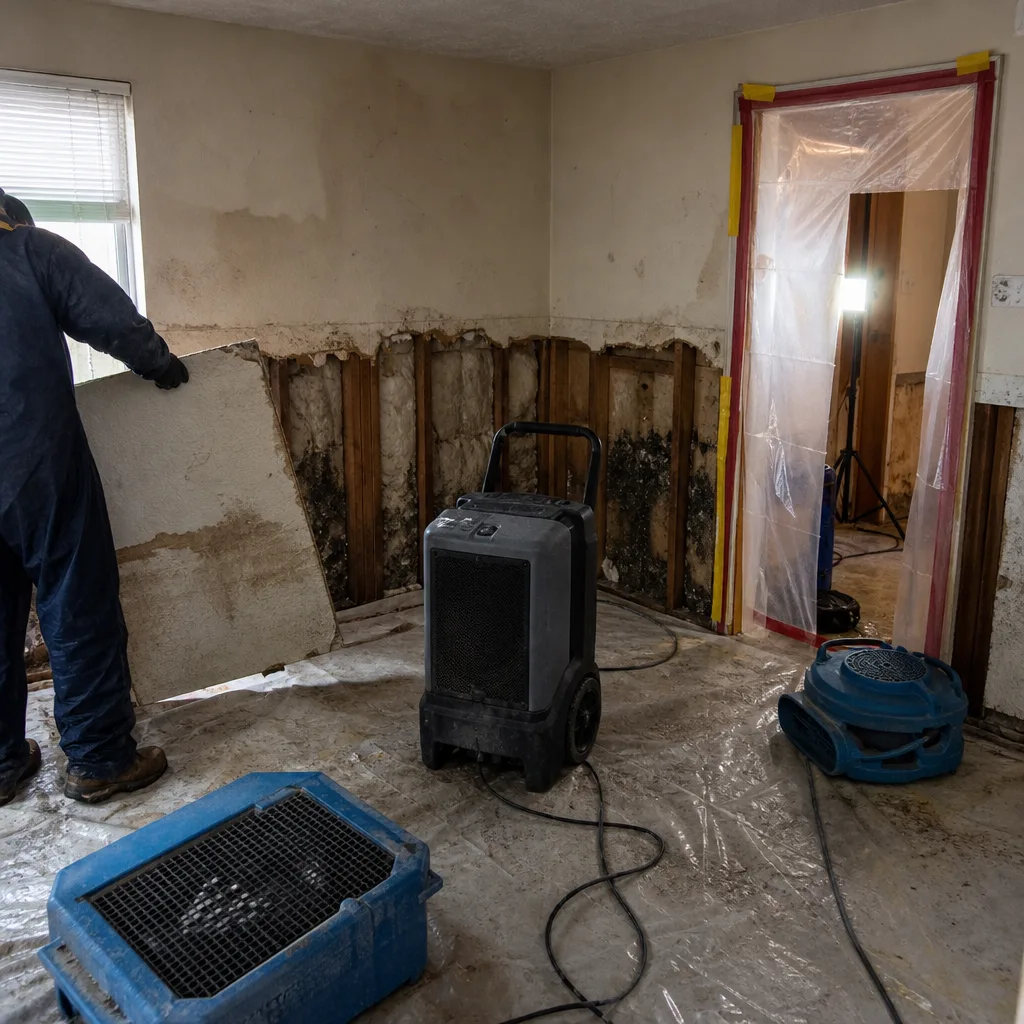 Before
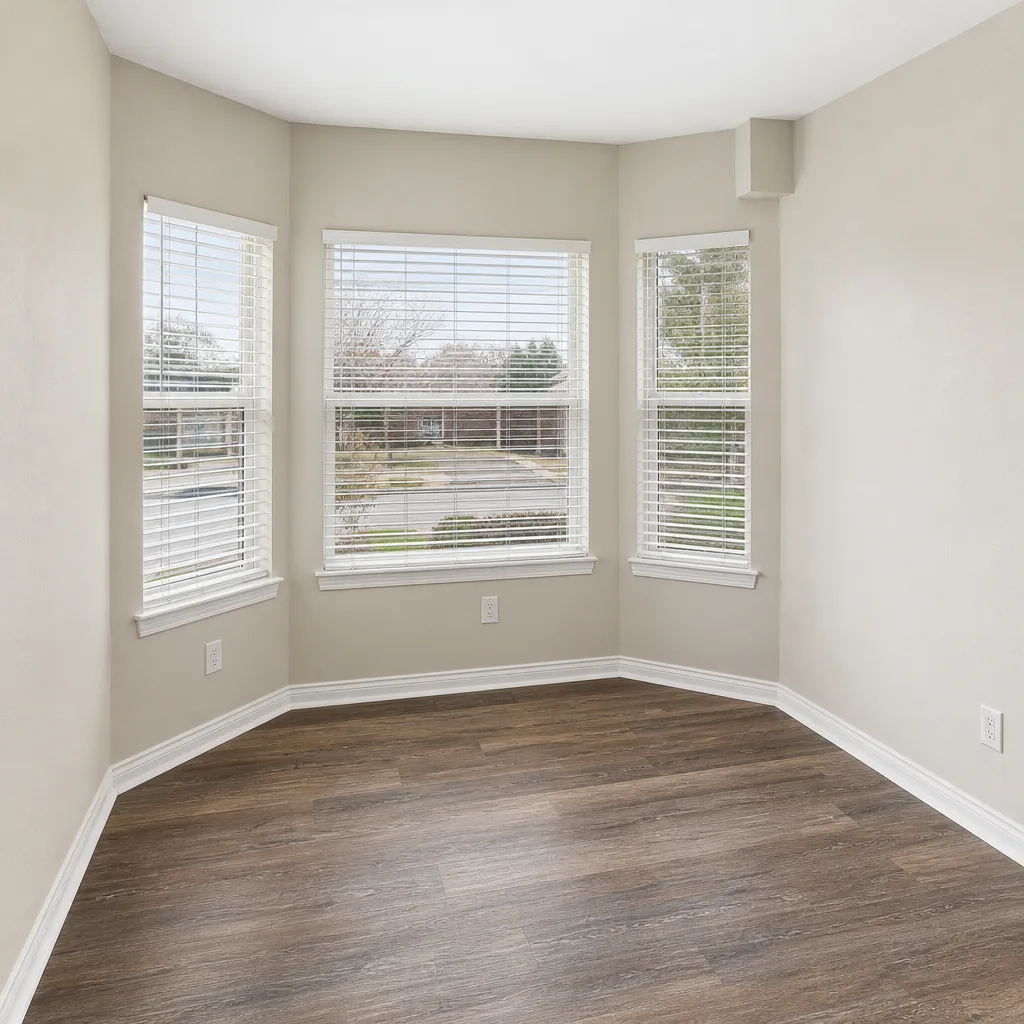 After
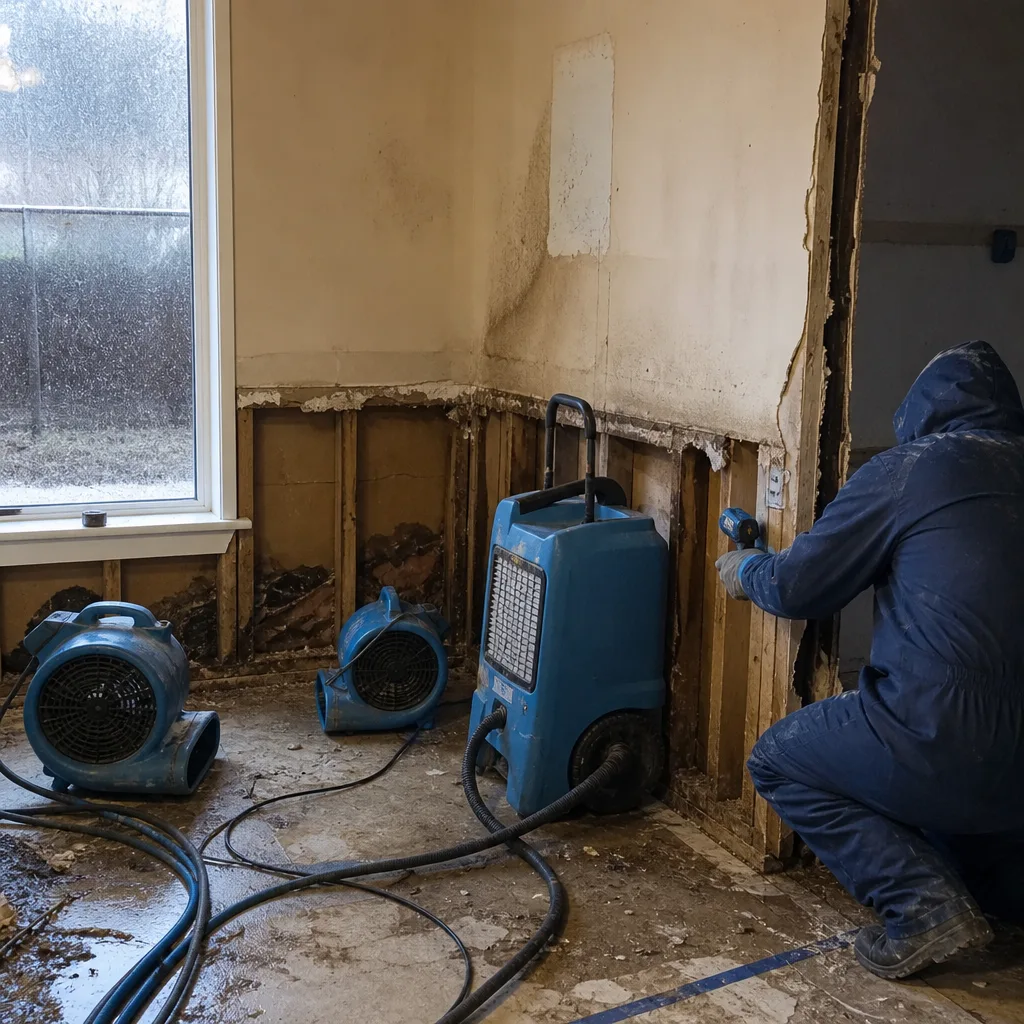 Before
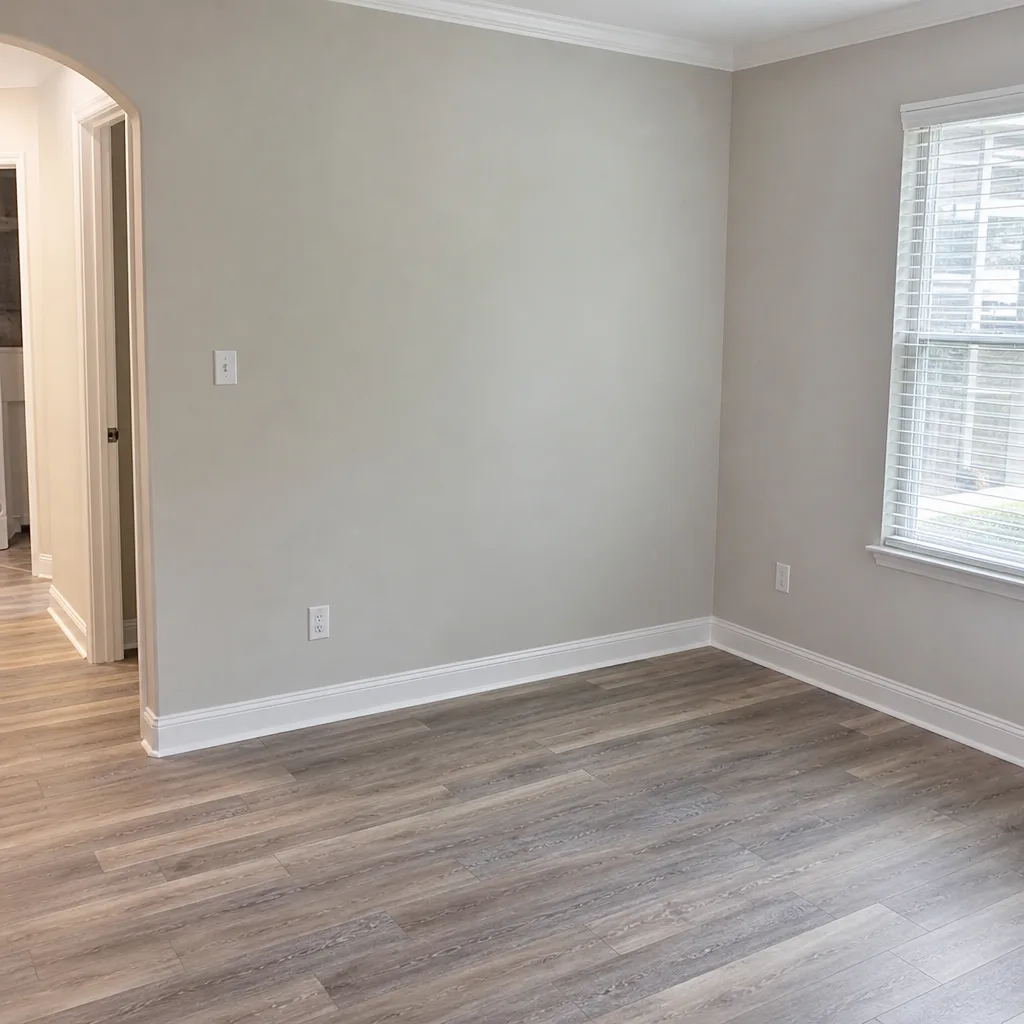 After